How It Works.Php
David Sterling
Managing Editor, Borrowing · Updated October 2026
David Sterling
Managing Editor, Borrowing · Updated October 2026
Imagine it is 2:00 AM on a Tuesday in 2026. You are sitting in your living room, scrolling through financial options on your phone, looking for a way to consolidate debt or fund a sudden home repair. You click see your rate and expect an answer almost instantly. Behind that seamless interface lies a complex web of server-side logic, API orchestrations, and rapid-fire data processing known colloquially in the industry as the how it works.php sequence. This process is what bridges the gap between a user's intent and a lender's decision.
In the current financial landscape of 2026, speed and accuracy are no longer optional; they are requirements. When you submit an application, you aren't just filling out a form; you are initiating a high-speed digital handshake. A typical user might look for loan amounts ranging from $5,000 to $50,000, with APRs that can vary widely between 6% and 36% depending on the lender's specific criteria. The goal of a modern matching engine is to take these variables and find the most compatible match in under sixty seconds.
This article will pull back the curtain on the technical infrastructure that makes this possible. We will explore how data moves from your screen to a lender's underwriting system, why security protocols are the bedrock of fintech, and what specific variables actually influence the results you see. Whether you are a borrower trying to understand the 'black box' of digital lending or someone interested in the architecture of modern finance, this deep dive provides the clarity needed to navigate these systems with confidence.
To understand how a matching engine functions in 2026, one must look past the user interface and into the server-side architecture. Most modern fintech platforms utilize highly scalable, event-driven architectures to handle thousands of simultaneous requests. When a request hits the server, it is processed through several layers: validation, enrichment, routing, and finally, response generation.
The first layer involves strict data validation. Before any information is sent to a lender, the system must ensure that the input is formatted correctly. For instance, if an applicant enters a phone number or social security number in an incorrect format, the backend logic will reject the request immediately to prevent errors downstream. This prevents wasted processing power and ensures that lenders only receive high-quality, actionable data.
Once validated, the data undergoes enrichment. This is where the 'magic' happens. The system might call upon external databases—such as those maintained by Experian or other credit bureaus—to supplement the information provided by the user. This creates a holistic view of the applicant's financial profile in real-time. Without this layer, the matching process would be far slower and significantly less accurate, often requiring manual document uploads that could take days rather than seconds.
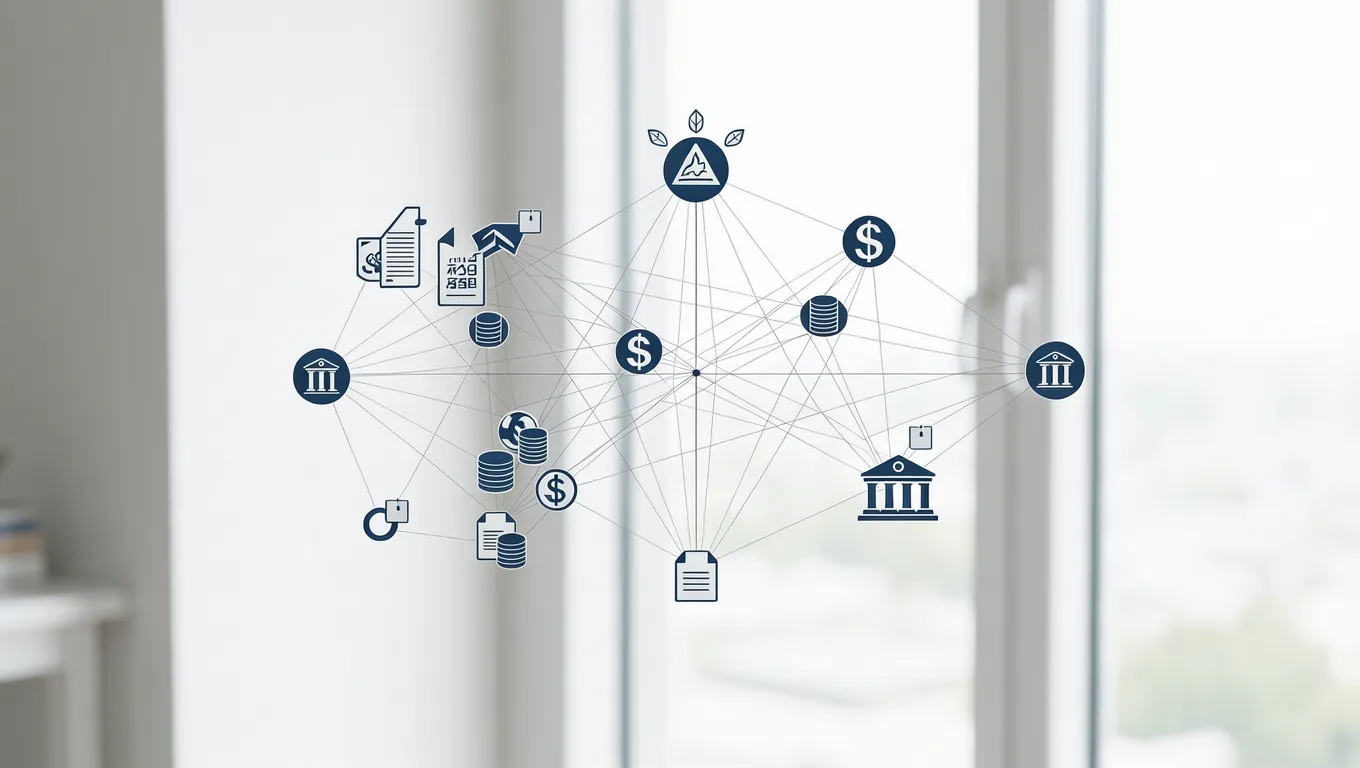
The journey of a loan application is essentially a series of data handoffs. Once you hit the submit button, your information is packaged into a standardized format—often JSON (JavaScript Object Notation)—which is then transmitted via an API (Application Programming Interface) call to potential lenders. This is where the concept of how it works.php becomes most tangible: it is the logic that determines which lender gets which piece of data.
Consider a practical example of this flow in action:
In an era where data is the most valuable commodity, security is not just a feature—it is the foundation. When you engage with a matching service, your sensitive information (like your SSN or bank account details) travels across the public internet. To protect this, fintech companies employ end-to-end encryption using advanced protocols like TLS 1.3. This ensures that even if data were intercepted, it would be unreadable to unauthorized parties.
Furthermore, the regulatory environment in 2026 is more stringent than ever. Agencies like the Consumer Financial Protection Bureau (CFPB) mandate strict guidelines on how consumer data must be handled and stored. Lenders are required to have robust 'data at rest' encryption, meaning that even when your information is sitting in a database waiting to be processed, it remains scrambled and protected.
A common misconception is that the matching site itself stores all your sensitive financial history permanently. In reality, many high-quality platforms use a method called tokenization. Instead of storing your actual credit card number or social security number, they store a 'token'—a random string of characters that represents that data. This way, even in the highly unlikely event of a breach, the stolen tokens are useless to hackers because they cannot be reversed back into the original sensitive information.
The core of any matching engine is its decision matrix. This is a mathematical model that weighs multiple variables to determine 'compatibility.' For example, if Lender A only funds people with credit scores above 700 and Lender B accepts scores down to 640, the algorithm must instantly sort applicants into those respective buckets. This isn't just about checking a box; it's about calculating probability.
The logic involves several key inputs:
Despite the sophistication of modern fintech, errors still occur. Most technical failures during a loan application aren't caused by the software itself, but by 'dirty data'—information provided by the user that is inconsistent or incorrect. The biggest mistake you can make is providing mismatched information between your application and your official records, such as an income amount that does not align with your tax returns or employment history.
When a system encounters conflicting data—for example, if you claim to earn $5,000 per month but your linked bank account shows sporadic deposits totaling $3,000—the automated logic may trigger a 'soft decline' or a manual review. Manual reviews are the enemy of the instant experience; they can add days or weeks to the process as a human underwriter must step in to verify the discrepancy.
To avoid these pitfalls, follow this decision framework for your next application:
As we look toward the remainder of 2026 and beyond, the boundary between 'checking a rate' and 'getting a loan' is blurring. We are moving away from legacy systems that rely on batch processing—where data is sent in large chunks at the end of the day—and toward true real-time streaming. This means that the 'how it works.php' logic is becoming increasingly integrated with Open Banking APIs.
Open Banking allows you to grant permission for a lender to view your transaction history directly from your bank, rather than requiring you to upload PDF statements. This reduces friction and significantly increases the accuracy of the underwriting process. In 2026, this technology has become the standard for premium lenders who want to offer the most competitive rates with the least amount of hassle.
Ultimately, the goal of these technological advancements is to create a more efficient, transparent, and accessible financial system. As the algorithms become smarter and the data flows become faster, the distance between a borrower's need and a lender's solution continues to shrink, making personal finance more intuitive for everyone involved.
If this option fits your situation, it's also worth comparing bad credit loans and personal loans for bad credit.